
In 2026, overall commodity performance remained flat, but three strategic minor metals—tantalum, germanium, and molybdenum—experienced a one-sided surge in prices. The significant price increases have already propagated down the supply chain into the electronics components sector. As one of the key downstream applications, the connector industry is now facing cost pressures driven by rising raw material prices.
On one hand, upstream resources are scarce and prices remain stubbornly high; on the other, downstream demand from AI, aerospace, and new energy sectors shows stark contrasts. Can costs be effectively passed down? What new developments will emerge in the industry landscape?
01
Supply and demand tighten simultaneously
Tantalum, germanium, and molybdenum see sharp price surges
According to Shanghai Ganglian data, by the end of May, domestic tantalum ingot prices had surged more than 150% year-to-date, germanium ingot prices rose 72.79%, and molybdenum concentrate increased by 31.8%, significantly outpacing major commodities such as copper and aluminum. This round of price increases has been driven by a combination of supply-demand imbalances, with supply concentrated geographically and facing substantial resistance to production expansion.
Over 80% of global tantalum production is concentrated in the Democratic Republic of the Congo, Rwanda, and Nigeria, where recurring geopolitical conflicts, safety incidents, and public health issues repeatedly disrupt mining operations, resulting in an annual supply growth rate for raw tantalum of less than 10%.
Germanium and molybdenum have successively been subject to export controls, with germanium exports tightened in 2023 and molybdenum exports restricted in 2025, reducing global supply from the source. Although China is the world’s leading producer of molybdenum, new mine development cycles are long, making it difficult to rapidly increase short-term production capacity.
Demand-side shifts have become a key driver of price increases. Small metals, previously used mainly in traditional chemical and metallurgical industries, are now being widely applied in emerging sectors such as AI computing power, advanced semiconductors, and commercial aerospace, with overall demand growth exceeding 20% and the supply-demand gap continuing to widen.
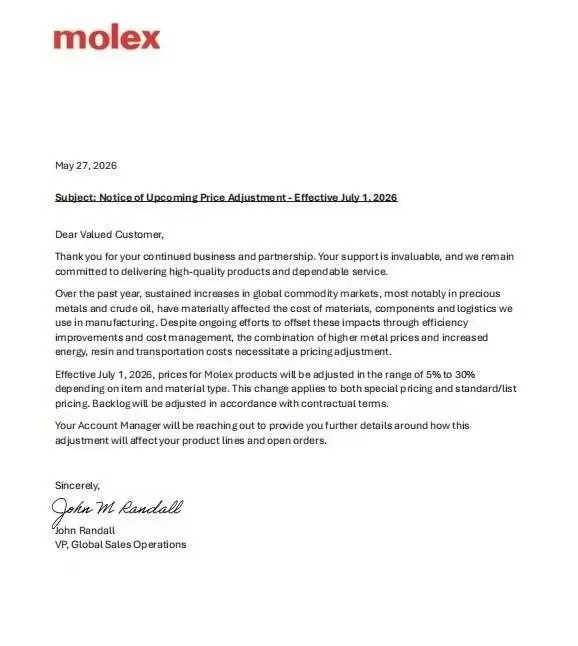
The most direct shockwave has arrived: pressured by rising raw material costs, international connector giant Molex has officially announced a 5% to 30% price increase on its products effective July 1. This move by the industry leader has formally sounded the starting gun for a wave of price hikes across the connector sector in the second quarter.
02
Material Structure Diversification
High-End Connectors Face Cost Pressure
From an industrial supply perspective, tantalum, germanium, and molybdenum are not universal raw materials for all types of connectors, but they are critical and essential materials for the production of high-end connectors.
Low-end consumer electronics connectors are primarily made of copper and plastic, using very little small metal; whereas in high-end connectors for computing power, aerospace, and automotive applications, small metal raw materials account for 12% to 22% of the cost.
Tantalum is primarily used to manufacture tantalum capacitors, which serve as essential internal components in AI servers and aerospace RF connectors. Thanks to their high-temperature and high-pressure resistance, these capacitors are difficult to replace with conventional ones, directly driving the strong demand for tantalum materials.
Germanium, thanks to its excellent optoelectronic properties, is used in fiber-optic communications and as a sensing substrate for internal connectors in low-orbit satellite systems. Global expansion of fiber-optic networks and the continuous increase in satellite launches are driving up germanium consumption.
Molybdenum processed into high-temperature alloys is widely used in the housings and terminals of 800V new-energy vehicle high-voltage connectors. As the penetration of high-voltage systems in new-energy vehicles accelerates, demand for molybdenum is steadily increasing.
Faced with a cost surge of up to 20%, leading companies such as Futaba and Ruike have managed to offset nearly 40% of the increased costs through pre-signed long-term supply contracts, allowing them to adjust pricing calmly. In contrast, smaller manufacturers lacking raw material reserves face direct cost reversals once their inventories run out, forcing them to cut low-end production capacity. As a result, industry resources will continue to consolidate toward the top players.
03
Divergence in Downstream Temperatures
Price increases show a bipolar pattern
Whether costs can be passed on depends entirely on the end customers’ reaction. The three high-growth sectors—AI computing power, commercial aerospace, and new energy vehicles—are experiencing rapid demand expansion, with downstream buyers showing relatively high acceptance of price increases.
AI server single-unit connector usage has significantly increased compared to traditional models, and cloud providers and server manufacturers are highly accepting of a 5%–15% price increase, even prepaying deposits to secure annual production capacity.
In satellite manufacturing, strong customization demands prompt aerospace companies to prioritize supply chain stability, enabling smooth cost pass-through.
The rollout of 800V high-voltage vehicles is accelerating, with automakers leveraging long-term annual contracts to spread out component cost increases, leading to steadily rising procurement demand.
In contrast, the traditional consumer electronics sectors such as smartphones and laptops are experiencing sluggish demand growth. Downstream brands are strictly controlling procurement costs, leaving connector manufacturers unable to raise prices. As a result, they must absorb rising costs by optimizing production processes and reducing manufacturing expenses, continuously compressing the profit margins of their related businesses.
Conclusion
In the medium to long term, overseas geopolitical disruptions combined with domestic export controls will make it difficult to resolve the supply bottlenecks for minor metals in the short term, and high raw material prices are expected to remain the norm over the next 2–3 years. Coupled with the fact that mine construction takes 2–3 years, the long-term expansion of aerospace, new energy vehicles, and other sectors will continue to drive demand for high-end connectors.
Future profits in the connector industry will accelerate toward consolidation among leading players who have secured high-quality downstream customers and long-term upstream supply agreements.
For small and medium-sized connector contract manufacturers, if they don’t decisively cut their loss-making low-end consumer electronics production now and pivot toward high-end niche markets such as AI computing power and automotive-grade products—where costs can be effectively passed on—they will face a double-edged squeeze from rising raw material prices and price pressures from OEMs.